The plan that helps you avoid a surprise rehab bill in Texas
If you are reading this after a stressful phone call about rehab costs, take a breath. That dread is real. People often worry they will choose the wrong program and get stuck with a bill they cannot manage. The safest move is not guessing. It is verifying insurance for addiction treatment in Texas before anyone agrees to admission.
Why your first call should be for insurance verification for rehab, not a blind admission request
The first call should focus on benefits, not feelings alone. You still need compassion, but you also need facts. Ask for insurance verification for rehab that checks plan type, behavioral health carve-outs, and network status. That simple step can prevent delays when you need medical detox, inpatient rehab, or an outpatient program. We hear this from families almost every week, especially when time feels tight and everyone is exhausted.
Here is the part most people miss. A rehab facility may sound ideal, yet your plan may treat it differently depending on the level of care. One center might accept your card but still need rehab prior authorization before treatment begins. Another might be out of network and still usable if your out-of-network benefits are strong. If you start with the benefits picture, you can compare drug rehab options with clearer eyes.
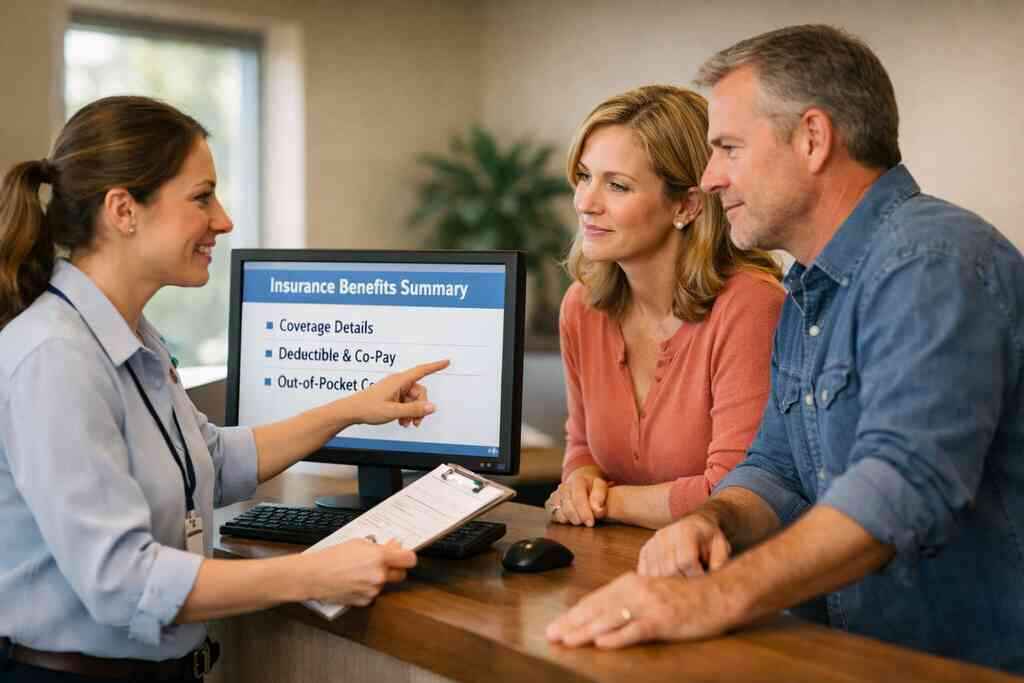
The coverage details that matter most for substance use disorder coverage, including deductible, copay, and out-of-pocket maximum
Coverage language can feel abstract, but these terms drive real decisions. Your deductible is what you pay before many benefits begin. Your copay is the fixed amount you may owe for visits or services. Your out-of-pocket maximum is the cap that limits what you spend in a plan period. For substance use disorder coverage, those numbers can decide whether treatment feels manageable or completely out of reach.
Families sometimes focus only on whether rehab is “covered.” That is not enough. You also need to know whether the plan applies separate behavioral health deductibles, whether there is coinsurance, and whether medical detox coverage has a different authorization path than inpatient rehab coverage. In Texas, some families gather these details late, after admission discussions already started. That creates panic. It is much better to ask early and keep notes.
When in-network rehab can cut costs and when out-of-network benefits may still be worth pursuing
In-network rehab often lowers your cost because the provider has contracted rates with the insurer. That usually means better predictability and fewer billing surprises. Still, out-of-network benefits can matter when the right clinical fit is not in network. If someone needs specialized dual diagnosis care or a specific level of care, the best option is not always the cheapest line item.
On one recent case, a caller near Fort Worth was torn between two programs. One was in network but had a long wait. The other was out of network and could admit sooner. That family asked the right question: what would the plan actually pay after deductible and coinsurance? That is the sort of practical thinking that protects both recovery and the budget. You do not need perfection. You need the best workable path.
Coverage ItemWhat to ConfirmWhy It MattersDeductibleRemaining amount and whether it applies to behavioral healthChanges your upfront costCopayPer-visit or per-day amountAffects repeated servicesOut-of-pocket maximumTotal annual limitProtects against runaway costsNetwork statusIn-network rehab or out-of-network benefitsStrongly affects billingAuthorizationRehab prior authorization requirementsCan delay or approve care### How rehab prior authorization works for medical detox coverage and inpatient rehab coverage
Prior authorization means the insurer wants clinical documentation before approving certain services. That may include diagnoses, history of use, withdrawal risk, and the requested level of care. For medical detox coverage, the insurer often wants proof that withdrawal management is medically necessary. For inpatient rehab coverage, they may ask why a lower level of care is not appropriate. This is standard, but it can feel intrusive when you are already overwhelmed.
The best documentation usually comes from an addiction assessment, recent treatment history, and current symptoms. If a loved one has repeated relapse warning signs, safety concerns, or unstable home conditions, say so plainly. Those details help the reviewer understand the clinical need. The cleaner the paperwork, the fewer delays you face. That is not glamorous, but it is essential.
The Texas-specific paperwork families often need before a level of care is approved
Texas families often need more than a simple phone call. Plans may ask for identification, policy details, a referral, clinical notes, and sometimes proof of current symptoms. If the person seeking care has been seen in an emergency department, those records can support the request. If a family is using an addiction intervention, notes from that process can also help explain urgency. The goal is to show why a specific level of care is necessary right now.
Here is a brief checklist that can keep the process moving:
- Insurance card and subscriber information
- Diagnosis or provisional diagnosis
- Current medication list
- Recent withdrawal symptoms or detox symptoms
- Prior treatment history
- Contact information for the chosen program
- Any discharge paperwork from recent medical visits
If you are juggling work, kids, and a phone on speaker, you are not alone. This paperwork step is genuinely annoying. It is also the bridge between uncertainty and actual treatment.
The benefit language behind medical detox coverage and withdrawal management
Medical detox is not the right first stop for everyone. It is the right start for some people and the wrong start for others. Insurance reviewers care about that distinction. They want to know whether withdrawal management is clinically necessary, safe, and matched to the person’s current risk. That is why benefit language matters so much for medical detox coverage and withdrawal management.
When detox symptoms make medical detox the safer starting point
Detox symptoms can range from uncomfortable to dangerous. Shaking, sweating, vomiting, insomnia, elevated heart rate, confusion, seizures, or hallucinations can all change the plan. Alcohol use disorder, benzodiazepine addiction, and fentanyl addiction can carry especially serious withdrawal risks. If someone needs round-the-clock monitoring, medical detox becomes more than a preference. It becomes a safety issue.
The question we get more than any other is simple: “Do we really need detox first?” Sometimes yes. Sometimes no. If a person can barely keep water down, cannot sleep, or has a history of severe withdrawal, that usually points toward supervised care. Insurance reviewers look for those details because they help justify withdrawal management. You should describe symptoms plainly, not minimize them.
What insurers usually look for in withdrawal management and addiction assessment documentation
Insurers usually want objective evidence. That may include an addiction assessment, a clinician’s notes, vital signs, substance use history, and recent attempts to stop. They often review whether the person meets criteria for a higher level of care and whether outpatient support would be too weak. The more specific the documentation, the easier the review.
Here is what almost no online guide mentions: vague language slows approvals. Saying someone is “doing badly” is not enough. Saying they have daily use, repeated failed quit attempts, escalating use, or dangerous withdrawal symptoms tells the story more clearly. That is true for drug addiction help and alcohol rehab alike. Clear documentation respects the reviewer’s process and protects your time.
How detox coverage can differ for alcohol rehab benefits versus opioid addiction treatment coverage
Alcohol rehab benefits and opioid addiction treatment coverage are not always handled the same way. An insurer may approve medical detox more readily for one substance and scrutinize another more closely. For example, opioid addiction treatment coverage may involve additional questions about medication-assisted treatment, while alcohol coverage may focus more on seizure risk and stabilization. The exact rules depend on the plan, not just the diagnosis.
This is where a careful conversation helps. Ask whether detox is billed as inpatient, observation, or a separate withdrawal management service. Ask whether the plan expects step-down care afterward. That matters because detox alone is rarely the whole answer. Recovery support usually needs therapy, aftercare planning, and a next level of care to keep momentum going.
Where fentanyl addiction treatment coverage and benzodiazepine addiction treatment coverage can become more complicated
Fentanyl addiction treatment coverage can become complex because withdrawal can be intense and clinically unstable. Benzodiazepine addiction treatment coverage can be even more sensitive because stopping too quickly may be dangerous. Insurers may look harder at the medical notes, recent use pattern, and monitoring needs. That extra scrutiny does not mean denial is inevitable. It means the documentation has to be stronger.
One family we helped understood this after a stressful weekend call. Their loved one had repeated failed attempts to stop and severe anxiety around withdrawal. Once the clinician documented the risks carefully, the conversation changed. The insurer was still the insurer, but the request made more sense on paper. That is why details matter so much in addiction treatment coverage.
What to ask before choosing a detox program near you in Texas
Before you choose a detox program near you, ask direct questions. You do not need polished language. You need answers. Start with these:
- Is medical detox covered by my plan?
- Do you require prior authorization?
- Is the program in network?
- What symptoms justify withdrawal management?
- Will you help with claims and appeals?
- What happens after detox?
If a program cannot answer clearly, keep looking. The right team should understand both care and billing. If you are comparing options, use find addiction treatment services near you in Texas as a starting point, then verify the benefits line by line. That approach saves time and lowers confusion.
Why inpatient rehab and residential treatment are not the same thing to an insurer
People often use “inpatient rehab” and “residential treatment” as if they mean the same thing. Insurers do not. The difference affects billing, approval, and length of stay. If you understand the distinction, you can ask better questions and avoid expensive confusion. That matters when the person needs structure, safety, and real medical oversight.
How ASAM criteria shape the level of care an insurer may approve
ASAM criteria help determine the proper level of care. They look at withdrawal risk, biomedical needs, emotional conditions, readiness to change, relapse potential, and recovery environment. Insurers may use those criteria, or something similar, to decide whether inpatient rehab coverage or residential treatment coverage is appropriate. That is why “needs help” is not enough on paper. The request has to match the clinical picture.
If someone has repeated relapse, unstable housing, or active co-occurring disorders, the ASAM framework may support a higher level of care. If someone is medically stable but still needs intensive structure, residential treatment may fit better. For a deeper walkthrough, families often benefit from understanding how ASAM criteria guides levels of care. That can make a denial or approval letter much easier to interpret.
The documentation that can support inpatient rehab coverage versus residential treatment coverage
Documentation should show why the requested level of care is necessary. For inpatient rehab, that may include medical instability, severe withdrawal concerns, or a need for close monitoring. For residential treatment, it may include relapse risk, unsafe home conditions, or inability to maintain sobriety in a less structured setting. The insurer is trying to match need to intensity.
In practice, strong notes from an addiction assessment help most. So do records showing failed outpatient attempts, emergency visits, or prior treatment episodes. If a clinician can explain why outpatient program coverage is not enough right now, the request becomes much stronger. The more clearly the story is documented, the easier the review.
When dual diagnosis coverage matters for co-occurring disorders treatment
Dual diagnosis coverage matters when substance use disorder and mental health symptoms appear together. That can include depression, anxiety, PTSD, bipolar symptoms, or other co-occurring disorders. If the plan sees only the addiction and ignores the mental health piece, the wrong level of care may be approved. That can slow recovery and create needless appeals.
A good program should screen for co-occurring disorders early. It should also understand how both conditions affect treatment planning. If you suspect trauma or mood symptoms are part of the picture, say so during verification. Families often feel unsure about mentioning everything. Please do. The insurance reviewer cannot approve what they do not understand.
How mental health and addiction coverage can change the treatment path for depression, anxiety, or trauma
Mental health and addiction coverage can change the path in subtle ways. A person may start in detox, move to residential treatment, then shift to a partial hospitalization program or IOP. Another person may need individual counseling, group therapy, and medication management from the beginning. If depression, anxiety, or trauma is active, that should shape the level of care. 
I have seen people get stuck because their coverage looked “good” on paper, but the requested program ignored the mental health piece. That creates friction. A better plan connects psychotherapy, addiction treatment, and medical support from the start. If you want a program that can address both sides of the issue, dual diagnosis care for co-occurring disorders is often the right lens.
What families should know about appealing a denial when the requested level of care is not approved
A denial is not the final word. It is a decision you can challenge. Start by asking for the reason in writing. Then compare that reason with the clinical documentation. If the insurer says the person can safely step down, but the notes show ongoing withdrawal risk or repeated relapse, you may have grounds for an appeal.
Appeals work best when they stay factual. Include symptom history, treatment history, and why a lower level of care is not appropriate. If possible, have the treating clinician support the appeal. Families often feel defeated here, but many denials come from incomplete information rather than true ineligibility. Keep going. The paper trail matters.
The outpatient math that determines whether PHP, IOP, or a standard outpatient program fits
Outpatient treatment is not a lesser option. For many people, it is the right level of care at the right moment. The real question is intensity. Partial hospitalization program, intensive outpatient program, and standard outpatient program services all serve different needs. If you know how insurers review them, you can better match care to coverage and avoid gaps.
When a partial hospitalization program makes more sense than stepping straight into weekly therapy
A partial hospitalization program can make sense when someone needs strong daytime structure without overnight care. PHP often includes multiple therapy blocks, medical monitoring, and daily clinical contact. That can be especially helpful after detox or residential treatment. It can also help if someone is stable enough to sleep at home but not yet ready for weekly therapy alone.
Weekly therapy may be too light for someone early in recovery. If the person has recent relapse warning signs, cravings, unstable routines, or co-occurring disorders, PHP coverage may fit better. partial hospitalization program and outpatient rehab in Texas is a useful phrase to keep in mind when comparing options. It captures the real decision: structure versus flexibility.
How intensive outpatient program and IOP coverage typically differ from PHP coverage
IOP coverage often looks different from PHP coverage because the intensity is lower. Intensive outpatient program services usually involve fewer hours per week, while PHP is closer to full-day treatment. Insurers may require proof that the person is stable enough for reduced structure. That is not a bad thing. It simply means the clinical step-down has to make sense.
A program may offer IOP after inpatient rehab, after residential treatment, or as a starting point for milder cases. Coverage often depends on whether the person still needs frequent support, but not round-the-clock oversight. If you want to compare the cadence and expectations, intensive outpatient program and outpatient treatment options can help frame the discussion. The wrong step is moving too fast just because it sounds easier.
What insurers may ask before approving outpatient program coverage for people leaving higher levels of care
Insurers often want to know why the person is ready to step down. They may ask whether withdrawal symptoms have stabilized, whether cravings are manageable, and whether the home environment is safe. They may also want proof of attendance and progress in prior treatment. That is especially true when someone is leaving medical detox, inpatient rehab, or residential care.
The better the discharge plan, the smoother the approval process. Ask about transportation, work schedules, childcare, and recovery support before choosing the next step. Those details matter more than many people realize. They can make outpatient program coverage more realistic and sustainable.
Why medication-assisted treatment coverage for Suboxone, methadone, or Vivitrol can affect the rest of the plan
Medication-assisted treatment coverage often changes the whole recovery plan. MAT coverage for Suboxone, methadone, or Vivitrol may determine how outpatient care is built. Some plans cover these medications well, while others require stricter authorization. That affects opioid addiction treatment coverage, relapse prevention, and the transition between levels of care.
If a program includes medication-assisted treatment, ask how prescriptions are billed and whether there is a preferred pharmacy. Ask how office visits, counseling, and labs are handled too. If you are comparing options, medication-assisted treatment with Suboxone or methadone can help you see why medication and therapy often work best together. The medication does not replace recovery work. It supports it.
How therapy coverage for cognitive behavioral therapy, dialectical behavior therapy, EMDR therapy, group therapy, family therapy, and individual counseling is usually reviewed
Therapy coverage is often bundled inside broader behavioral health benefits. That can include cognitive behavioral therapy, dialectical behavior therapy, EMDR therapy, group therapy, family therapy, and individual counseling. Insurers may not approve every service the same way. Some plans require medical necessity. Others limit session counts. Some allow one setting more easily than another.
This is where specificity helps. If trauma is present, EMDR therapy may be clinically appropriate. If family conflict fuels relapse, family therapy may matter. If thinking patterns drive substance use, cognitive behavioral therapy may be a strong fit. For a closer look at one common modality, cognitive behavioral therapy for addiction recovery is a practical starting point. The main point is simple: therapy should match the problem, not just fill a schedule.
The next move when you are comparing rehab options in Texas and want the claim to work
By the time you compare programs, the pressure can feel intense. You may be balancing urgency, money, and fear all at once. That is exactly when people get pulled in by marketing copy instead of clinical fit. Slow down just enough to check the right boxes. The claim has to work, but the care also has to work.
How to choose a rehab by matching levels of care benefits and clinical needs instead of marketing copy
A strong rehab choice starts with levels of care, not slogans. Ask where the person fits: medical detox, inpatient rehab, residential treatment, PHP, IOP, or standard outpatient program. Then match that against your behavioral health benefits. The best program is the one that fits the clinical need and the insurance reality at the same time.
Here is a simple way to think about it:
- Confirm diagnosis and current risk.
- Verify in-network rehab status.
- Ask about prior authorization.
- Match the level of care to ASAM needs.
- Review discharge and aftercare planning.
If you are unsure where to begin, best ways to pay for rehab with insurance can help frame the conversation. The right choice is usually not the loudest one. It is the one that respects both care and coverage.
What to confirm about prescription drug addiction coverage, cocaine addiction coverage, heroin addiction coverage, and alcohol use disorder coverage
Different substances can trigger different coverage questions. Prescription drug addiction treatment coverage may involve pain medication histories and tapering concerns. Cocaine addiction coverage may lean more heavily on therapy and relapse prevention. Heroin addiction coverage and fentanyl addiction treatment coverage often intersect with MAT and withdrawal management. Alcohol use disorder coverage may emphasize detox safety and ongoing counseling.
That is why a broad addiction assessment matters. It helps the insurer understand the actual pattern, not just the label. Families sometimes hesitate to say the full truth, especially around prescription drug misuse. Please do not hold back. Accuracy protects the person seeking care. It also improves the odds of approving the right level of support.
How relapse prevention planning and aftercare planning can shape approval for sober living or transitional housing
Insurers do not always cover sober living or transitional housing the same way they cover treatment. Still, relapse prevention planning and aftercare planning can influence the whole care path. If the clinical team explains why step-down support is necessary, the transition becomes more defensible. That matters after detox, residential treatment, or PHP.
A smart aftercare plan may include outpatient counseling, recovery coaching, 12-step programs, SMART Recovery, and medication follow-up. It may also include job support, transportation planning, or family sessions. Those pieces lower chaos. They also show that treatment is not ending; it is shifting. aftercare planning and relapse prevention support can help families see how recovery continues after the first admission.
Why recovery support options like 12-step programs, SMART Recovery, and holistic addiction treatment still matter to the insurance conversation
Recovery support is not fluff. It can be part of a credible plan. Some insurers view 12-step programs, SMART Recovery, and holistic addiction treatment as supportive services rather than stand-alone treatment. Even so, these supports can strengthen continuity of care and reduce gaps between higher and lower levels of care. They matter because recovery is lived between appointments.
If you are asking whether your plan “covers” these supports, the answer may be mixed. But they still belong in the conversation. A person leaving inpatient rehab may do better with community support, family therapy, and structured meetings. That does not replace clinical care. It reinforces it. For many people, that combination is where stability starts to feel possible.
The checklist for getting addiction treatment near me moving today without losing momentum on coverage
If you need action today, keep it simple. Do not try to solve every variable at once. Start with the insurance and then move to the clinical fit. Use this checklist:
- Call for insurance verification for rehab.
- Ask for in-network rehab and out-of-network benefit details.
- Confirm whether prior authorization is needed.
- Request the recommended level of care in writing.
- Ask about detox, MAT, and therapy coverage.
- Clarify discharge and aftercare planning.
- Save every reference number and name.
If you want a place to start, how to verify rehab insurance coverage for addiction treatment can help organize the process. You do not have to figure this out alone, and you do not have to figure it all out today. Start with one phone call, one benefits check, and one honest conversation about what is safest now.
Frequently Asked Questions
Question: How can Addiction Treatment Services help me verify insurance for addiction treatment before I choose a rehab in Texas?
Answer: Addiction Treatment Services helps simplify the first and most important step: insurance verification for rehab. Instead of guessing whether a program is in network or whether you have out-of-network benefits, you can use our directory and educational resources to compare addiction treatment options with more confidence. We help you think through the details that matter most, including substance use disorder coverage, rehab prior authorization, deductible, copay, and out-of-pocket maximums. That can make a big difference when you are paying for rehab in Texas and trying to avoid surprise bills.
Question: What should I know about medical detox coverage, withdrawal management, and detox symptoms when looking at Top 5 Insurance Tips for Rehab in Texas 2026?
Answer: Medical detox coverage often depends on whether withdrawal management is medically necessary, which is why detox symptoms and a clear addiction assessment matter so much. If someone is experiencing severe alcohol use disorder symptoms, fentanyl addiction, benzodiazepine addiction, or opioid addiction concerns, a supervised setting may be the safer starting point. Addiction Treatment Services can help you understand how medical detox, inpatient rehab, and step-down care may fit together within your insurance for addiction treatment. We also help you learn what questions to ask about MAT coverage, including Suboxone coverage, methadone coverage, and Vivitrol coverage, so you can compare programs more clearly.
Question: How do I know whether inpatient rehab, residential treatment, PHP, or IOP coverage is the right fit for my situation?
Answer: The right level of care usually depends on current symptoms, relapse warning signs, home stability, and what the insurer will approve based on ASAM criteria and clinical documentation. Inpatient rehab coverage is often considered when medical monitoring or stronger structure is needed, while residential treatment coverage may be appropriate when someone needs a highly supportive environment without the same level of medical oversight. For many people, partial hospitalization program and intensive outpatient program options can offer a practical step-down path, especially when outpatient program coverage is available and the person is medically stable. Addiction Treatment Services helps you compare levels of care without relying on marketing language alone, so you can better understand which option fits both the clinical need and the insurance benefits.
Question: Does Addiction Treatment Services help with dual diagnosis coverage and co-occurring disorders treatment for mental health and addiction coverage?
Answer: Yes, and this is one of the most important areas to understand when looking at rehab insurance coverage. Many people facing substance use disorder also need support for depression, anxiety, trauma, or other co-occurring disorders, and that can affect which treatment setting is appropriate. Addiction Treatment Services explains how dual diagnosis coverage may influence access to individual counseling, family therapy, group therapy, cognitive behavioral therapy, dialectical behavior therapy, and EMDR therapy. We focus on helping people see how mental health and addiction coverage work together, because treatment for addiction is often more effective when both sides of the picture are addressed in the plan.
Question: How does Addiction Treatment Services support families comparing rehab options, aftercare planning, sober living, and recovery support after treatment?
Answer: We help families think beyond admission and into the full recovery process. That means reviewing relapse prevention planning, aftercare planning, and whether sober living or transitional housing may be part of the next step after medical detox, inpatient rehab, residential treatment, PHP, or IOP. We also encourage people to look at recovery support options such as 12-step programs, SMART Recovery, and holistic addiction treatment as part of a broader plan. If you are trying to choose a rehab and want to understand how the claim will work as well as what happens after discharge, Addiction Treatment Services gives you the information you need to make a more informed decision. Our goal is to help you find addiction treatment near me resources that are practical, compassionate, and aligned with both clinical needs and insurance realities.